This is our 40th post on this blog, and we are announcing the $600k milestone!
We’ve been tracking the portfolio at $590k since 2 months ago, but we were stalled for quite a while. Some of the possible reasons behind the flat market include: federal fund rate increase, U.S. war in Iran ft. energy crisis, worries about the ridiculous AI CapEx, etc. Nevertheless, we are excited to see growth in our portfolio (for now).
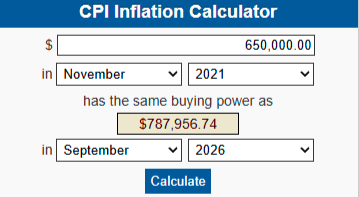
HOWEVER, within 9 months, the CPI inflation calculator has pushed our FIRE goal by THIRTY THOUSAND DOLLARS. Compared to the 10 months between February 2025 and December 2025, where inflation only added $11k to our overall goal.
Even though our portfolio grew $100k in the past 9 months, after adjusting for inflation, we technically netted only $70k…
With that said, here’s the updated numbers as of October 31st, 2026:
| Account | March 28th, 2024 | March 26th, 2025 | February 2nd, 2026 | October 31st, 2026 |
|---|---|---|---|---|
| HYSA | $27,455 | $38,727 | $39,977 | $40,795 |
| Regular Savings | $40,852 | $46,518 | $65,500 | $65,692 |
| Total Savings | $68,307 | $85,245 | $105,477 | $106,487 |
| Account | March 28th, 2024 | March 26th, 2025 | February 2nd, 2026 | October 31st, 2026 |
|---|---|---|---|---|
| BF Taxable | $66,106 | $88,116 | $138,927 | $163,540 |
| BF Roth IRA | $33,906 | $47,426 | $68,316 | $80,524 |
| BF Trad IRA | $11,383 | $13,008 | $14,835 | |
| BF Roth 401k | $7,882 | $18,681 | $27,857 | |
| BF HSA (excluded previously) | $9,879 | $15,475 | ||
| GF Taxable | $36,296 | $61,025 | $106,270 | $141,047 |
| GF Roth IRA | $9,287 | $17,819 | $30,275 | $39,577 |
| GF Trad IRA | $5,436 | $7,246 | $8,237 | |
| GF HSA (excluded previously) | $8,978 | $12,915 | ||
| Total Investments | $145,595 (sans Trad IRAs) | $239,090 (sans HSAs) | $401,580 | $504,007 |
Portfolio Allocation
Currently, our investment portfolio consists of 73% in ETF and 27% in individual stocks. Earlier this year, as semiconductor stocks continued to soar, we derisked our portfolio by selling a good chunk of TSMC (Taiwan Semiconductor Manufacturing Company) and LRCX (Lam Research) after they ran up. They used to be our 2 biggest holdings.
We put the profit into SCHD and SCHG (2 ETFs that we already owned), and bought SCHY and FNDF to diversify into the international markets.
We’re still concentrated in US market (72.4%) as of October 31st and will probably continue to shift more towards a 65-35 US/International (or even 60-40).
Dividend
Our dividends are increasing steadily. Last year, we received a total of $4,100.19 in dividends (from what we track in our taxable and Roth IRA accounts). Year-to-date, we received $4,881.78, and we expect to have a big payout in Q4 2026 that would push us to ~$6,800 for 2026. If we reached this amount, it would be around a 65% increase compared to last year.
Quick summary of dividend over the years:
| Year | Total Dividend (Taxable and Roth IRA) |
|---|---|
| 2021 | $38 |
| 2022 | $1,610 |
| 2023 | $2,525 |
| 2024 | $3,521 |
| 2025 | $4,100 |
| 2026 YTD | $4,882 |
What’s Next?
In the new year, we should probably start thinking about our exit plan (in life).
Similar to this year, we’ll continue to increase our ETF positions in 2027 to derisk away from individual holdings and increase our exposure to the international markets.
This would push our dividend higher because 3 out of 4 ETFs that we hold have higher dividend yield, good dividend growth history, while also having good capital gain growth. Theoretically, this would provide us with more cash flow that would supplement our income in the future.
Overall, we hit two important milestones this year ($500k and $600k)! That alone is a huge accomplishment, and we’re glad we started this FIRE journey early. We’ll see how long it’ll take for us to get to $700k!